Share of profit of a deceased partner's will be debited to :
Answer & explanation
Correct answer: option 4
The correct answer is Option (4) → Profit and Loss Suspense A/c
Note: The given answer is as per the official NTA Answer Key. For this question, Option (2) could also be a possible answer, as explained below.
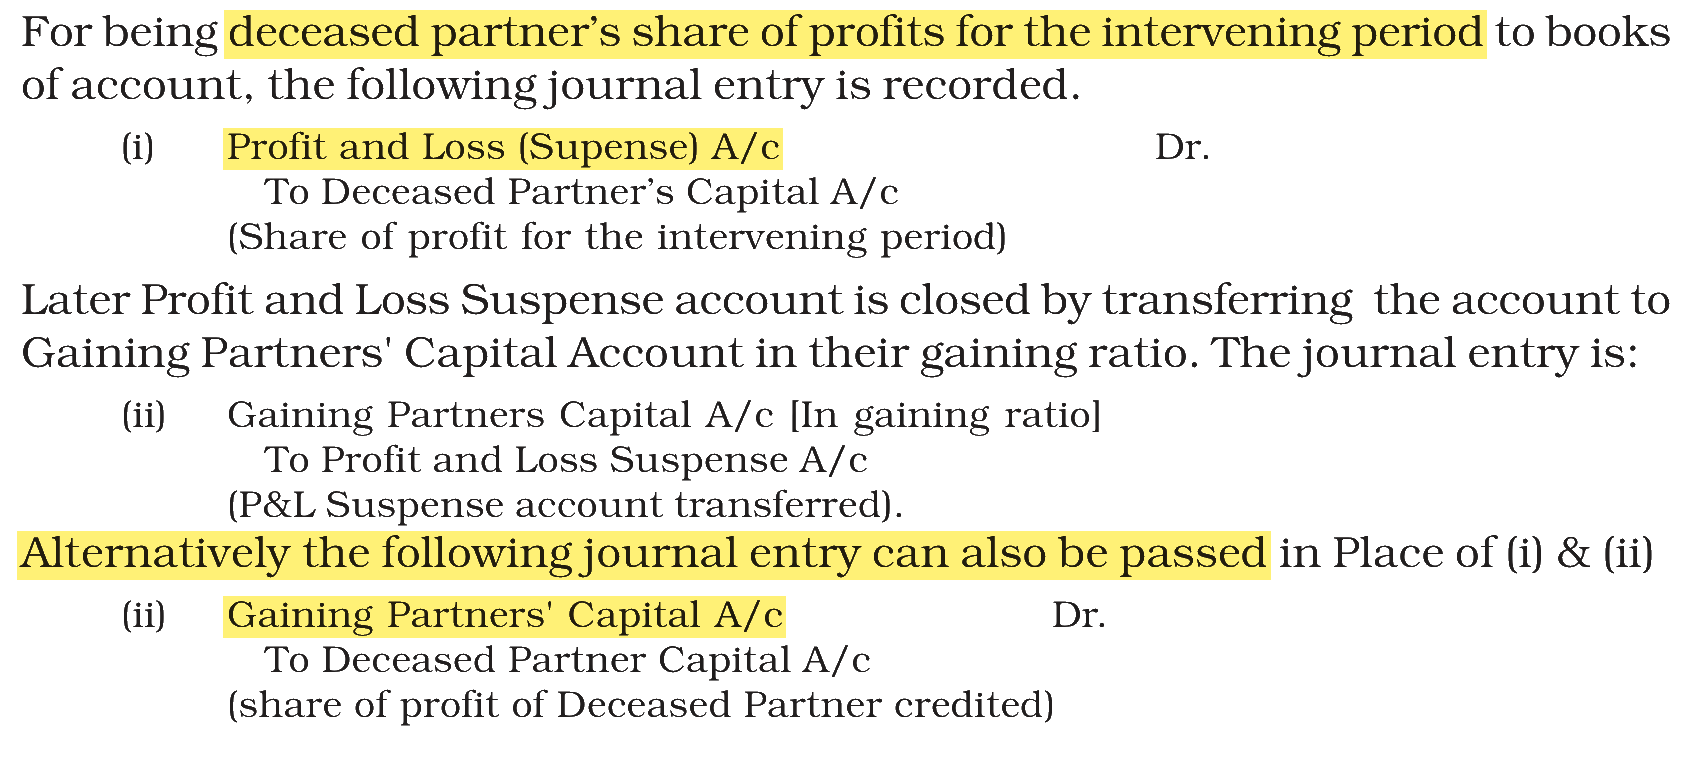
A partner who dies during the year is entitled to his share of profit up to the date of death. The books are not closed on that date, so his share is brought in through a Profit and Loss Suspense Account: it is debited, and the deceased partner’s capital account is credited. The suspense account is later closed to the gaining partners’ capital accounts in their gaining ratio. One combined entry is also allowed in place of these two: the gaining partners’ capital accounts are debited directly.
Option (1) Profit and Loss Appropriation A/c — Incorrect. No appropriation account is prepared on the date of death; the year’s profit is not yet known.
Option (2) Partner's Capital A/c — Should also be correct, though not the answer given by NTA. Under the alternative entry the share is debited to the continuing (gaining) partners’ capital accounts.
Option (3) Revaluation A/c — Incorrect. The Revaluation Account records changes in the values of assets and liabilities, not a share of profit.
Option (4) Profit and Loss Suspense A/c — Correct. It is the account debited with the deceased partner’s share of profit for the intervening period.
NCERT (2026-27 edition):
|