The correct answer is Option (1) → (D), (E), (C), (B), (A)
(D) Net profit before tax and extraordinary items — the starting point of operating activities.
(E) Adding and Deducting the changes in working capital — turns operating profit into cash from operations.
(C) Purchase of Machinery — an investing activity, shown after operating activities.
(B) Repayment of Bank Loan — a financing activity, shown after investing activities.
(A) Closing Balance of Cash — the last line of the statement.
NCERT (2026-27 edition):
Ascertaining Cash Flow from Operating Activities – “… As stated earlier, while working out the cash flow from operating activities, the starting point is the ‘Net profit before tax and extraordinary items’ and not the ‘Net profit as per Statement of Profit and Loss’. Income tax paid is deducted as the last item to arrive at the net cash flow from operating activities.” NCERT (2026-27 edition):
Ascertaining Cash Flow from Operating Activities – “… Other important adjustments relate to changes in working capital which are necessary (i.e., items of current assets and current liabilities) to convert net profit/loss which is based on accrual basis into cash flows from operating activities. Therefore, the increase in current assets and decrease in current liabilities are deducted from the operating profit, and the decrease in current assets and increase in current liabilities are added to the operating profit so as to arrive at the exact amount of net cash flow from operating activities.” NCERT (2026-27 edition):
Cash from Investing Activities – “As per AS-3, investing activities are the acquisition and disposal of long-term assets and other investments not included in cash equivalents. Investing activities relate to purchase and sale of long-term assets or fixed assets such as machinery, furniture, land and building, etc. Transactions related to long-term investment are also investing activities.” NCERT (2026-27 edition):
Cash from Financing Activities – “As the name suggests, financing activities relate to long-term funds or capital of an enterprise, e.g., cash proceeds from issue of equity shares, debentures, raising long-term bank loans, repayment of bank loan, etc.” NCERT (2026-27 edition):
Cash Flow Statement 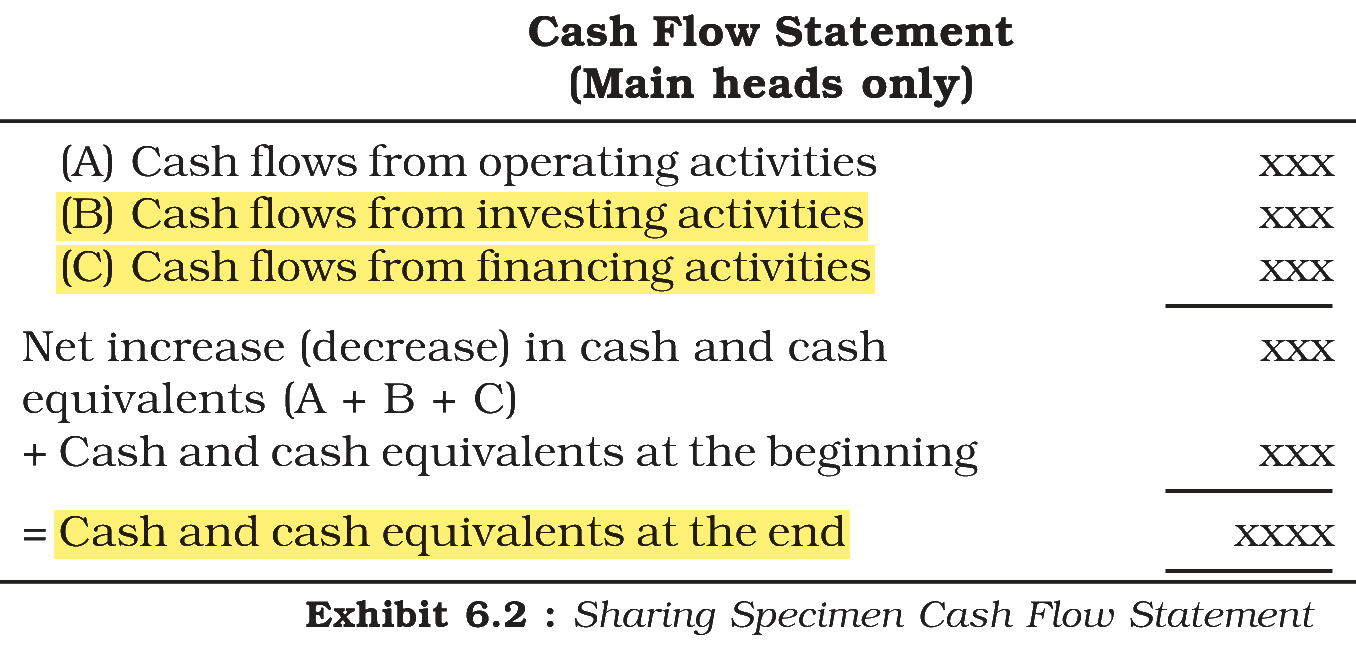
|
