On Dissolution of a firm, Investment fluctuation reserve appearing in the balance sheet will be:
Answer & explanation
Correct answer: option 2
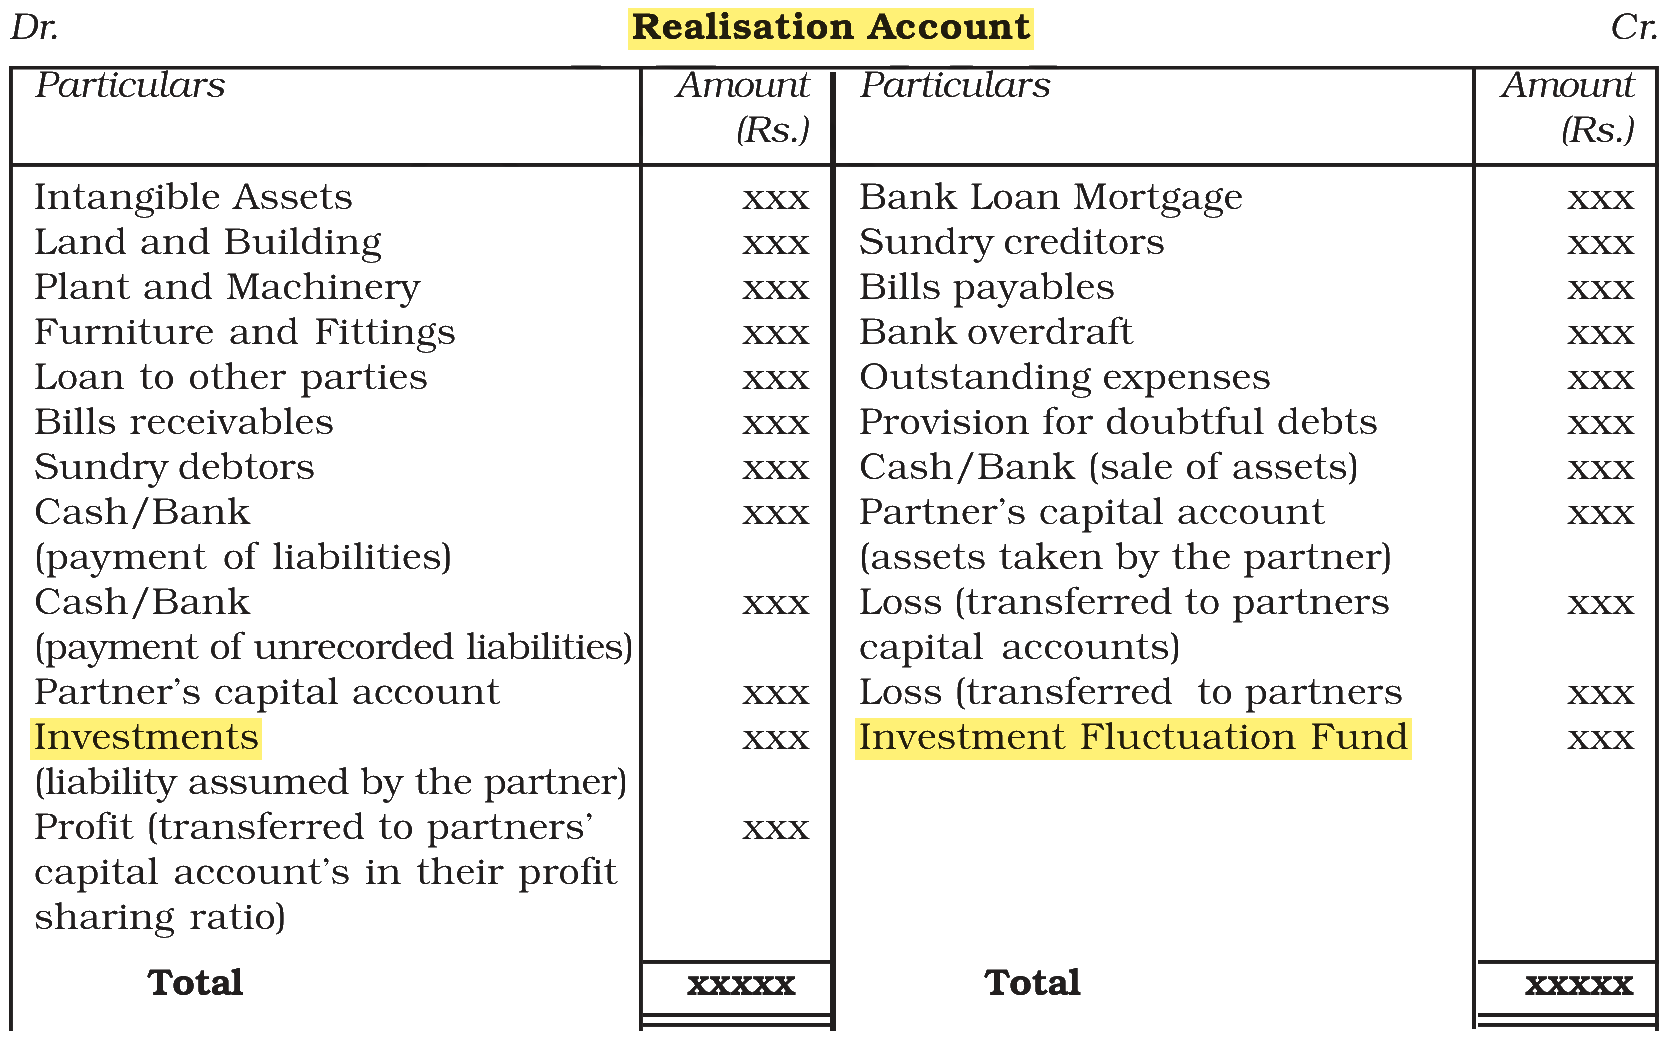
The correct answer is Option (2) → Credited to realisation A/c with full value
On dissolution the investments are transferred at their book value to the debit side of the Realisation Account. The Investment Fluctuation Fund (reserve) was kept aside to meet a fall in the value of those investments, so it is transferred in full to the credit side of the Realisation Account, where it stands against the investments; any fall in value is then absorbed there, and the balance reaches the partners as part of the profit or loss on realisation.
Option (1) Debited to Realisation A/c with full value — Incorrect. The fund is a credit balance (a reserve); the investments themselves are debited, not the fund.
Option (3) Debited to all Partners’ Capital A/c in their profit sharing ratio — Incorrect. A credit balance like this fund cannot be debited to the partners; only an accumulated loss is.
Option (4) Credited to all Partners’ Capital A/c in their profit sharing ratio — Incorrect. General reserve and other free reserves go straight to the capital accounts, but the Investment Fluctuation Fund is tied to the investments and is shown on the credit side of the Realisation Account.
NCERT (2026-27 edition):
|