At the time of dissolution of partnership firm, following accounting adjustments are considered : -
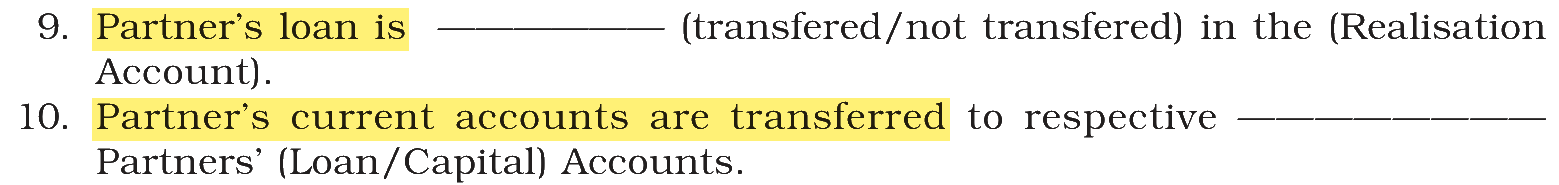
A. Partner's current A/c are transferred to respective partner's loan A/c.
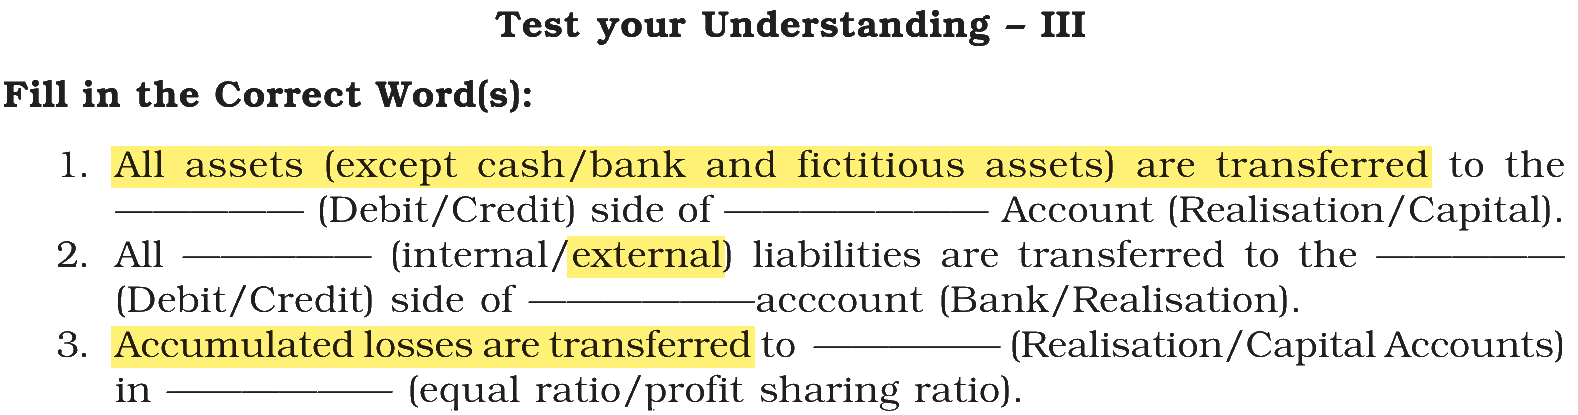
B. Accumulated losses are transferred to partners capital A/c in profit sharing ratio.
C. All assets except cash and fictitious assets are transferred to debit side of Realisation A/c.
D. Partner's loan are transferred to Realisation A/c.
E. All external liabilities are transferred to the credit side of Realisation A/c.
Choose the correct answer from the options given below :
Answer & explanation
Correct answer: option 4
The correct answer is Option (4) → B, C and E only
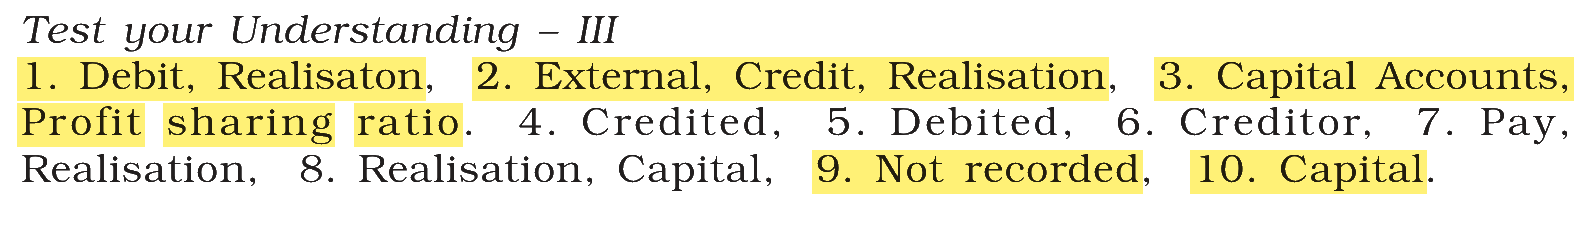
(A) Partner's current A/c are transferred to respective partner's loan A/c. — False. Current accounts are transferred to the partners’ capital accounts.
(B) Accumulated losses are transferred to partners capital A/c in profit sharing ratio. — True.
(C) All assets except cash and fictitious assets are transferred to debit side of Realisation A/c. — True.
(D) Partner's loan are transferred to Realisation A/c. — False. A partner’s loan is not transferred to Realisation Account; it is paid directly after outside liabilities.
(E) All external liabilities are transferred to the credit side of Realisation A/c. — True.
Note: The book’s answer key gives “Not recorded” for item 9, which means “not transferred” (the word the blank asks for).
NCERT (2026-27 edition):
NCERT (2026-27 edition):
NCERT (2026-27 edition):
|